CIPS vs. SWIFT: Dedollarization or Global Public Good?
Posted on | August 26, 2026 | No Comments
Citation APA (7th Edition)
Pennings, A.J. (2026, Aug 27) CIPS vs. SWIFT: Dedollarization or Global Public Good? apennings.com https://apennings.com/digital-geography/the-100-trillion-debt-era-mmt-as-permission-sact-as-engine/
Introduction
The competition between China’s Cross-Border Interbank Payment System (CIPS) and the Western financial infrastructure represented by Society for Worldwide Interbank Financial Telecommunication (SWIFT) is often described as a technological contest where one payment network is replacing another. But the deeper issue is who gets to coordinate economic activity around the world.
The contest between CIPS with the Chinese Renminbi on one side and SWIFT messaging system on the other is not a simple competition between two currencies. It is a collision between two fundamentally different financial architectures that reflect divergent visions of the international political economy.
In this post, I explore where global commerce and finance are heading by suggesting we look past headline exchange rates and examine the underlying financial plumbing. It is important to review the systemic philosophies, technical mechanisms, trade patterns, and vulnerabilities that separate a sovereign hub like CIPS from a (mostly) global commons like the Society for Worldwide Interbank Financial Telecommunication (SWIFT), which is heavily oriented towards the USD.[1]
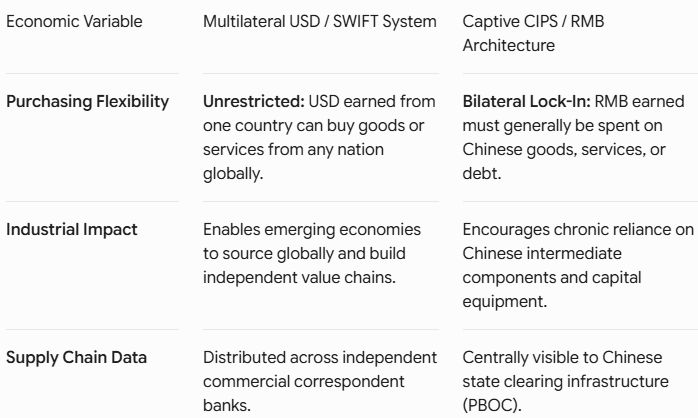
At the level of systemic philosophy, the two networks serve opposite economic models. CIPS and the RMB are designed as a national and sovereign hub whose primary function is to anchor bilateral trading partners directly into the Chinese domestic economy and financial system. It operates as an instrument of strategic sovereignty and industrial coordination, establishing a secure, state-monitored channel that connects counterparties directly to Beijing.
In contrast, SWIFT and the USD financial system function as a flawed but globally enabling commons. Built to facilitate multilateral commerce between third-party nations, the dollar infrastructure operates as universal, open-ended connective tissue that allows two non-US entities to finance and settle trade without touching either domestic banking system. For instance, a trade between a Brazilian exporter and a South Korean importer using USD.
This techno-ideological divide is mirrored in their functional roles. CIPS is an integrated messaging and Real-Time Gross Settlement engine supervised by the People’s Bank of China. It does not merely transmit communications; it executes the final balance-sheet movement of funds in Renminbi within a single sovereign architecture. SWIFT, by contrast, is a universal financial messaging cooperative that holds no funds and settles no accounts. It delivers standardized transaction instructions, leaving the actual netting and real-time final settlement (when needed) to domestic clearing systems, specifically CHIPS and Fedwire in New York.
These mechanical differences shape entirely distinct trade dynamics across the globe. CIPS fosters a bilateral, radial pattern of trade where nations selling commodities or raw materials to China accumulate RMB balances, which they must then recycle into Chinese manufactured exports, industrial equipment, or state engineering contracts. Value flows inward toward and outward from the central Chinese node in Beijing.
The USD-SWIFT system drives multilateral, distributed trade, where companies hold dollar liquidity because it can be deployed anywhere in the world to buy energy and other commodities, settle contracts, or invest in third-party markets without restriction.
This structural divergence is enforced by the degree of capital account openness in each home country. China operates a managed and restricted capital account, using strict cross-border controls to insulate its domestic financial system from external volatility and preserve monetary independence. The US system rests on a fully open capital account, underpinned by the multi-trillion-dollar US Treasury market, which provides global central banks and institutions with the deepest, most liquid secondary market in history.
Inevitably, each architecture carries its own defining structural vulnerability. For CIPS and the RMB, the primary bottleneck is trapped surpluses where foreign counterparties accumulate non-convertible currency that cannot easily be redeployed outside trade with China.
For SWIFT and the USD, the vulnerability is sanction weaponization, using global clearing access and messaging cutoffs as tools of geopolitical coercion. This has incentivized non-aligned nations to build parallel financial circuits, trading the immense liquidity of an open commons for the political insulation of a sovereign hub.
In sum, CIPS is not simply a replacement for SWIFT. It is better understood as an attempt to build a China-centered payment and settlement infrastructure around the renminbi, while still using substantial parts of the existing global financial architecture. That distinction actually makes the geopolitical argument more interesting.
CIPS, SWIFT, and the Politics of Financial Infrastructure
The US dollar has supplied much more than a currency. It has supplied a global infrastructure for trade, credit, settlement, liquidity, and price discovery. SWIFT is only one component of that infrastructure. Dollar clearing, correspondent banking, CHIPS, Fedwire, Treasury markets, Eurodollar lending, FX markets, and the institutions surrounding them form a much larger system. Its extraordinary value comes from network effects. Companies in Vietnam, Mexico, Bangladesh, Brazil, Nigeria, Germany, and China can transact with one another without constructing a separate bilateral monetary system for every trading relationship.
That is one reason the dollar has been such an important enabling infrastructure for global development. A Vietnamese exporter does not have to trust the Vietnamese dong to trade with Mexico; a Bangladeshi manufacturer does not need to hold pesos to sell to a Mexican buyer. Dollar liquidity provides a common intermediate medium through which enormous numbers of otherwise unrelated transactions can be coordinated.
CIPS is not SWIFT 2.0
China created CIPS in 2015 to promote cross-border renminbi settlement and internationalize the RMB. It has grown substantially. By the end of 2025, CIPS reported 193 direct participants and 1,573 indirect participants across 124 countries and regions, with its broader banking network reaching roughly 190 countries.
But the distinction between payment settlement and financial messaging matters. CIPS is a settlement system, whereas SWIFT is primarily a messaging network. Moreover, CIPS remains interconnected with SWIFT and the existing international financial system. The US-China Economic and Security Review Commission noted that CIPS still relies heavily on SWIFT messaging while maintaining its own messaging capability for direct participants.
This suggests that China’s strategy is not to destroy SWIFT. It is to construct a parallel RMB-centered financial geography that can operate with less dependence on US-controlled infrastructure when necessary. That is a rational strategy from Beijing’s perspective. The problem is what happens when the payment network becomes part of a larger system of economic dependence.
The Lesson of Russian Energy
Europe’s experience with Russian energy provides an important analogy. For decades, Europe benefited enormously from Russian natural gas. The arrangement was economically efficient as Russia supplied relatively inexpensive energy while European industries and consumers received dependable fuel. But the invasion of Ukraine demonstrated that economic interdependence can become geopolitical leverage.
The European Commission subsequently described Russia’s energy exports as having been “weaponised” and embarked on REPowerEU to diversify supplies, reduce fossil-fuel consumption, and eliminate excessive dependence on Russian energy.
The lesson was not that Russian gas was technologically inferior. Quite the opposite. It was economically attractive precisely because the infrastructure was deeply integrated. The problem was that integration created vulnerability when the supplier possessed political objectives that could conflict with the interests of the customer.
This is the crucial question for CIPS. If a country such as Bangladesh, Vietnam, Mexico, Indonesia, or another developing economy increasingly conducts trade through a Chinese-controlled monetary infrastructure, it may gain cheaper access to RMB liquidity and Chinese markets. But it could also acquire a new form of dependency.
The concern is not necessarily that Beijing would immediately “control” these economies. That would be too strong. Rather, the architecture could give China greater leverage over the conditions under which economic relationships operate.
Payment infrastructure can influence who can transact, which currencies can be used, which banks can participate, how compliance is performed, how information moves, and ultimately which economic relationships are easiest or most difficult to maintain.
USD dependence to Infrastructure Dependence
This is where the comparison with the dollar becomes particularly revealing. The dollar system also possesses enormous power. The United States can use sanctions, export controls, financial restrictions, and access to dollar clearing as instruments of statecraft. That power should not be minimized. But an important difference exists between a globally distributed infrastructure and a nationally centered infrastructure.
The dollar system has become extraordinarily useful precisely because participants from many countries can use it without becoming economically subordinate to the United States in every other respect. A Mexican manufacturer can trade with a Vietnamese supplier. A Bangladeshi garment exporter can receive dollars from an American retailer. A Brazilian commodity producer can sell to China. A Nigerian company can purchase equipment from Europe.
The dollar functions as a kind of common computational and monetary language. That does not make it politically neutral. It makes it infrastructurally universal.
CIPS offers something different. It is an alternative monetary infrastructure centered on China’s currency, banking system, and geopolitical relationships. As its network expands, it could become increasingly useful for countries wishing to reduce exposure to US sanctions and dollar clearing. The US Congressional research and security literature explicitly identifies this sanctions-resilience function as one reason CIPS matters.
This creates a paradox. The world may want a more multipolar monetary system because excessive dependence on one country creates vulnerabilities. But replacing one dominant network with several competing monetary blocs can increase transaction costs.
Imagine a world divided among dollar, RMB, euro, rupee, and perhaps regional digital-currency systems. Every multinational corporation would need to manage multiple liquidity pools, payment systems, compliance regimes, exchange-rate exposures, collateral arrangements, and settlement infrastructures. The result could be less global liquidity, not more.
This is particularly important for developing economies. Their principal problem has historically not been a lack of currencies. It has been a lack of access to deep, liquid, internationally accepted currencies. Note the different circumstances faced by countries in the tiered global USD system.

The dollar’s great infrastructural advantage is that it allows countries to participate in global markets without having to possess currencies that are themselves globally trusted.
The SACT Interpretation
The global spreadsheet logic/dollar system can be understood as a gigantic coordination system I call the Substitution-Abstraction-Symbolic Computing-Telecom Synchronization (SACT) stack. Substitution replaces innumerable bilateral monetary relationships with a common settlement medium. Abstraction converts heterogeneous national currencies, commodities, contracts, and financial claims into interoperable currency-denominated units. Symbolic computation allows those units to be priced, collateralized, netted, cleared, and redistributed through financial institutions and markets. Telecommunications synchronization connects the resulting financial states across borders.
SWIFT, CHIPS, Fedwire, correspondent banks, Treasury markets, FX markets, and the Eurodollar system therefore constitute something considerably larger than a payment network. They form a global monetary information infrastructure.
CIPS is an attempt to construct an alternative version of that infrastructure. The geopolitical question is therefore not simply “Will CIPS replace SWIFT?” It is which financial infrastructure will provide the computational grammar through which global economic activity is coordinated?
And this brings us back to the Russian energy analogy. Europe eventually concluded that a highly efficient infrastructure could become dangerous when excessive dependence on one supplier created political vulnerability. The EU’s post-2022 policy explicitly emphasized diversification and resilience rather than simply replacing Russian gas with another single source. That may be the more useful lesson for monetary infrastructure as well. The future should be interoperable, not bipolar.
The answer to CIPS probably should not be an attempt to preserve an exclusive American monopoly over international payments. Nor should the world simply substitute Chinese monetary infrastructure for American infrastructure. The better objective is interoperability without political capture.
Treasury-backed dollar stablecoins could potentially become an important part of that architecture. Rather than requiring every country to construct a separate correspondent-banking system, regulated digital dollars could provide globally accessible dollar liquidity through mobile wallets and blockchain settlement networks. At the same time, interoperability with other currencies and payment systems could prevent the emergence of another closed monetary bloc.
The ultimate competition, then, is not between SWIFT and CIPS. It is between open global liquidity and politically conditioned liquidity. The dollar’s historical advantage has been that its infrastructure became so widely distributed that it ceased to look like an American product and became part of the operating environment of world commerce. CIPS is increasingly important because China wants a greater measure of control over that environment.
The central challenge for the next monetary order is therefore to preserve the extraordinary network effects that made global trade possible and affordable while preventing any single state from turning financial infrastructure into an instrument of dependency. That is perhaps the strongest argument for extending dollar liquidity, not simply preserving the existing dollar system, but making dollar liquidity more distributed, digital, interoperable, and accessible to a developing world.
Notes
[1] I started this inquiry in my Master’s thesis (August 1986) on SWIFT and other technological innovations that emerged in the late 1970s and early 1980s. I recently decided to compare SWIFT with new Chinese fintech innovations, specifically looking at which would provide a global commons as enabling infrastructure for global development. Interestingly, at the time the name for SWIFT was Society for Worldwide Interbank Funds Transfer.
AI Prompt(s) Describe the competition between CIPS replaces SWIFT. The USD has been the enabling infrastructure for global development. Make the argument that CIPS is just a way for China to control its competitors such as Bangladesh, Mexico, and Vietnam. Remember why Europe rejected Russian energy. Too many strings attached.
© ALL RIGHTS RESERVED
Not to be considered financial advice. AI is often used, and results are thoroughly interrogated. Links are used for some citations. Views are my own and do not express the stances of my employers, past or present.
 Anthony J. Pennings, PhD is a Professor at the Department of Technology and Society, State University of New York, Korea and a Research Professor for Stony Brook University. He teaches AI and broadband policy. From 2002-2012 he taught digital economics and information systems management at New York University. He also taught in the Digital Media MBA at St. Edwards University in Austin, Texas, where he lives when not in Korea.
Tags: China’s Cross-Border Interbank Payment System (CIPS) > CIPS > Cross-Border Interbank Payment System (CIPS) > Dedollarization > Global Public Good > Public Good > Substitution-Abstraction-Symbolic Computing-Telecom Synchronization (SACT) > The Society for Worldwide Interbank Financial Telecommunications (SWIFT)
Comments
Categories
Referencing this Material
About Me
Professor (full) at State University of New York (SUNY) Korea since 2016. Research Professor for Stony Brook University. Moved to Austin, Texas in August 2012 to join the Digital Media Management program at St. Edwards University. Spent the previous decade on the faculty at New York University teaching and researching information systems, digital economics, and global political economy
You can reach me at:
anthony.pennings@gmail.com
apennings70@gmail.com
anthony.pennings@sunykorea.ac.kr

About me
Writings by Category
- artificial intelligence
- automatrix
- blockchain
- books and films
- characteristics of digital media
- creative cities
- creative industries
- crisis communications
- cryptocurrencies
- cultural Industries
- data analytics and meaning
- democratic political economies
- digital coordination
- digital destruction
- digital geography
- digital media economics
- digital media management
- digital monetarism
- digital spreadsheets
- disaster risk management
- disruption
- dystopian economies
- educational innovations
- electric money
- enabling frameworks
- enterprise systems
- financial news
- financial technology
- food policy and security
- futurists
- geopolitical risk
- global communications
- global e-commerce
- health IT
- how IT came to rule the world
- intellectual property
- journalism
- meaning makers
- meaningful play
- media strategies
- mobile technologies
- multimedia
- political economies in sf
- political economy of media
- public administration
- science and technology studies
- sensing technologies
- smart new deal
- social media
- space systems
- spreadsheet logic
- strategic communications
- sustainable development
- technologies of meaning
- technology management
- telecom policy and net neutrality
- telegraphic political economy
- telelearn/telework
- the cold war
- the smith effect
- uncategorized
- visual literacy and rhetoric
